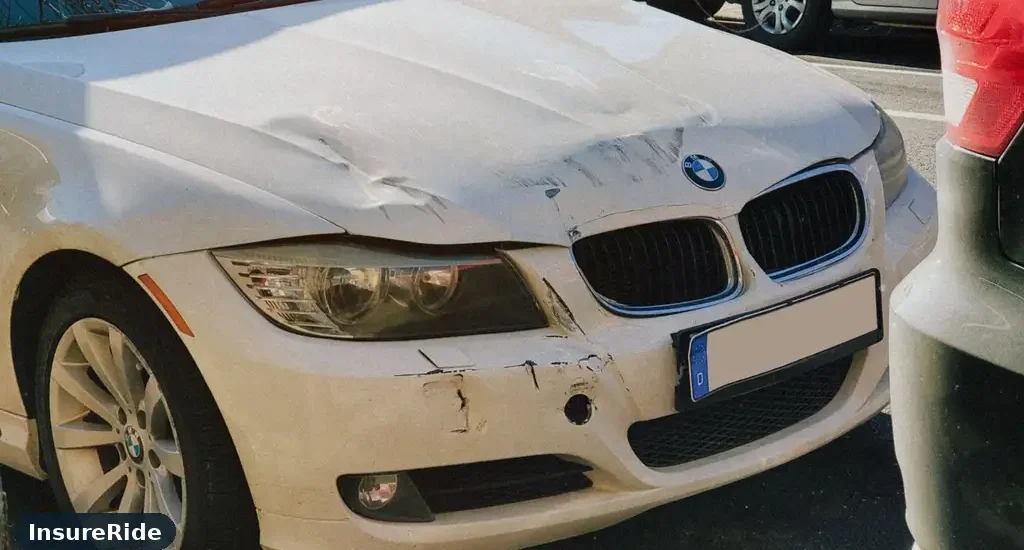
After an accident or damage to a car, most drivers want one simple answer: how long will the claim take. The honest answer is that it depends. A small, clear claim with good evidence can move quickly, while a complex claim with injuries, disputed fault or hard to source parts can take much longer.
Knowing the stages of a claim helps set realistic expectations. It also shows where delays usually appear and what a driver can do to keep things moving. This guide walks through the usual timeline, the factors that slow claims down, and the steps that help a claim reach a decision sooner.
How a typical claim moves through the stages
Most car insurance claims follow the same broad stages. First the claim is reported and logged. Then the insurer checks the policy, confirms the cover in place and gathers the basic facts. After that comes assessment of the damage, a decision on the claim, and then repair, replacement or payment.
The early stages are often the fastest. Reporting a claim and getting a claim number can happen on the same day. The assessment stage usually takes longer because it depends on inspections, repairer availability and parts. The final stage depends on whether the car can be repaired or needs to be written off.
Claims with a clear cause and clear evidence tend to pass through these stages without much friction. Claims where fault is unclear, where more than one vehicle is involved, or where the damage is hidden tend to spend longer at the assessment stage while the insurer gathers more information.
What happens in the first days after a claim
In the first days the insurer usually confirms the policy details and the type of cover held. The driver may be asked for the date, time and place of the incident, a description of what happened, and the details of any other people or vehicles involved. Photos of the damage are often requested at this point.
If the car is not safe to drive, the insurer will usually discuss recovery and storage. Some policies include a courtesy car while repairs are arranged, and some do not. It is worth checking this early so transport plans can be made while the claim is assessed.
A claim handler is normally assigned once the basic facts are recorded. That person becomes the main point of contact, and most updates will come through them. Keeping a note of the claim number, the handler’s name and the date of each call makes later follow up much easier.
Assessment, repair and settlement
Assessment is the stage where the insurer works out what the damage is and what it will cost to put right. This may involve an inspection by an approved repairer, an independent assessor, or a review of photos and repair estimates. Simple damage to a bumper or a wing mirror is usually assessed quickly.
Once the assessment is complete, the insurer decides whether the car will be repaired or written off. If it is repaired, the car goes to a repairer and the work is booked in. The time this takes depends on the repairer’s workload, the availability of parts and whether any further damage is found once work begins.
Settlement follows the repair or the write off decision. For a repair, the insurer usually pays the repairer directly, minus any excess the driver owes. For a write off, the insurer pays the value of the car as set out in the policy, again minus the excess. Payment timing can vary, so it helps to ask what to expect and when.
What slows a claim down
Missing information is one of the most common causes of delay. If photos are unclear, if the other driver’s details are missing, or if the description of events is incomplete, the insurer has to go back and ask for more. Each round of questions adds days to the timeline.
Disputed fault is another common delay. When two drivers disagree about what happened, the insurer may need statements, dashcam footage or independent evidence before it can decide. Claims involving more than one insurer can also take longer because each side has to review the evidence.
Parts and repair capacity can slow a claim even when the decision is straightforward. Some models need parts that are not held locally, and some repairers have waiting lists. Hidden damage found during repair can add further time because the estimate has to be revised and approved again.
Injury claims usually take the longest of all. Medical reports, treatment and recovery all take time, and a fair settlement cannot be reached until the full effect of the injury is understood. These claims often run for months rather than weeks, and rushing them can work against the person who was hurt.
How to keep a claim moving
Reporting the claim promptly is the simplest way to keep it moving. Most policies ask for claims to be reported as soon as reasonably possible, and early reporting gives the insurer the best chance to gather fresh evidence while details are still clear.
Clear evidence helps a great deal. Photos taken at the scene, the registration numbers of vehicles involved, contact details for witnesses and any dashcam footage all reduce the number of questions the insurer needs to ask. Keeping copies of everything sent to the insurer is also wise.
Responding quickly to requests for information keeps the claim on track. If the insurer asks for a document or a statement, sending it the same day avoids a pause while the claim waits. If a document cannot be found, saying so straight away is better than leaving the request unanswered.
Staying in contact matters too. A short call or message every week or so to check progress is reasonable, and it can surface a missing document or a decision that is waiting on a reply. Keeping notes of who was spoken to and what was agreed helps if the claim later needs to be chased.
What to do when a claim takes too long
If a claim seems to be stuck, the first step is to ask the claim handler what is holding it up. There is often a specific reason, such as a missing report, a part on order, or a decision waiting for a senior review. Knowing the reason makes it possible to help remove the block.
If the answer is unclear or nothing changes, asking for the claim to be reviewed by a supervisor is a reasonable next step. A short written summary of the claim, the dates of contact and the outstanding issue can help a supervisor see the position quickly.
Keeping a clear record throughout the claim is useful if the delay continues. Dates of calls, names of people spoken to, copies of letters and emails, and the dates documents were sent all build a timeline that shows what has happened and when.
Most insurers have a formal complaints process for claims that have stalled. Using it does not have to mean the relationship breaks down. It simply asks the insurer to look again, and it creates a clear record that the delay has been raised.
This guide explains how cover generally works. It is not personal financial advice. Check your own policy wording before you decide.
How long does a simple car insurance claim take?
A simple claim with clear damage and good evidence can often be assessed and repaired within a few days to a couple of weeks. The exact time depends on the repairer, parts availability and how quickly information is provided. More complex claims take longer.
What is the most common reason a claim is delayed?
Missing or unclear information is the most common cause. Photos that do not show the damage clearly, missing details of the other driver, or an incomplete account of the incident all lead to extra questions, and each round of questions adds time to the claim.
Can a driver speed up a car insurance claim?
A driver can help by reporting the claim promptly, sending clear photos and documents, and replying quickly to requests for information. Keeping notes of every contact also helps. The driver cannot control repairer capacity or parts supply, but good evidence removes many avoidable delays.
What should a driver do if a claim takes months?
Ask the claim handler for the specific reason for the delay, then ask for a supervisor review if nothing changes. Keep a written record of all contact and documents sent. If the delay continues, use the insurer’s formal complaints process to ask for the claim to be reviewed.