When a claim is made, the insurer does not simply pay whatever is asked for. The claim is assessed against the policy wording, the evidence available and the facts of the incident. That assessment decides whether the claim is covered, how much is paid and who is held responsible.
Understanding how that process works helps a driver give the insurer the information it needs and know what to expect. This guide explains the main steps in a claim assessment, the evidence insurers look at, and the reasons a claim may be reduced or refused.
The first check is the policy cover
The first thing an insurer checks is whether the policy covers the incident that happened. The level of cover matters here. A third party policy does not cover damage to the driver own car, while a comprehensive policy usually does. A policy with fire and theft cover may cover a stolen car, but it may not cover accident damage to the driver own car.
The insurer also checks whether the policy was active at the time of the incident, whether the premium had been paid, and whether the driver was covered to drive the car. If the policy had ended, or if the driver was not covered, the claim may be refused.
Exclusions are checked at this stage too. Most policies exclude certain situations, such as driving under the influence, using the car for a purpose not covered by the policy, or damage caused by wear and tear. If the incident falls under an exclusion, the insurer may refuse the claim or pay only part of it.
Checking the details given on the policy
The insurer also checks the details given when the policy was bought. The address, the drivers, the mileage, the car details and any modifications are compared with the facts at the time of the claim. If a detail is wrong, the insurer may treat the policy as having been bought on incorrect information.
That does not always mean the claim is refused. In some cases, the insurer may pay the claim but adjust the amount to reflect the premium that should have been paid. In other cases, especially where the error looks deliberate, the claim may be refused and the policy may be cancelled.
This is why accuracy at the time of buying matters so much. A small error that seems harmless when the policy is bought can become a serious problem at claim time. Drivers should check their policy documents when they arrive and correct any errors straight away.
Evidence from the scene
Evidence from the scene is a central part of the assessment. Photos of the damage, the position of the cars, the road layout and any road signs help the insurer understand what happened. A clear set of photos taken soon after the incident is often more useful than a long written description.
Witness statements are also valuable. A witness who saw the incident and has no connection to either driver can help settle a disagreement about what happened. The insurer may contact witnesses to confirm what they saw.
Police reports, where available, are another source of evidence. A police report may record the facts, the statements of those involved and any action taken. Dashcam footage, if available, can be very helpful too, because it shows the moments before and during the incident.
How fault is decided
Fault is decided by weighing the evidence from both sides. The insurer looks at the statements of each driver, the photos, the witness accounts, the police report and any other evidence. In many cases, the facts are clear and fault is agreed quickly. In other cases, the two drivers disagree, and the assessment takes longer.
Fault is not always all or nothing. In some incidents, both drivers share some responsibility. An insurer may decide that one driver was mainly at fault and the other partly at fault, and the claim may be settled on that basis. The split depends on the facts of each case.
If the two insurers disagree about fault, they may negotiate between themselves. That can take time, and the driver may need to wait for a decision. Keeping in touch with the insurer and providing any extra information that is asked for helps the process move forward.
Assessing the damage and the cost
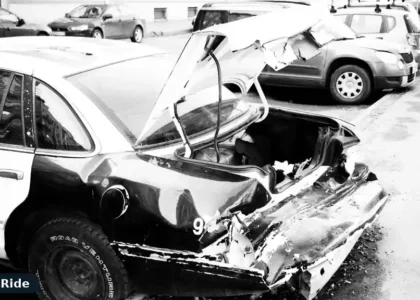
Once cover and fault are considered, the insurer assesses the damage. That usually involves an inspection of the car by an assessor or an approved repairer. The assessor looks at the damage, decides what needs to be repaired or replaced, and estimates the cost.
The insurer checks whether the damage is consistent with the incident described. If the damage does not match the account given, the insurer may ask for more information or investigate further. Damage that was already there before the incident is not usually covered as part of the new claim.
If the cost of repair is higher than the value of the car, the insurer may decide that the car is a write off. In that case, the insurer pays the market value of the car at the time of the incident, less the deductible, rather than paying for repairs. The driver may be offered the chance to keep the car, but the payout is usually reduced if they do.
Why a claim may be reduced or refused
A claim may be reduced if part of the damage is not covered, if the car value is lower than the driver expected, or if the deductible is applied. The deductible is the amount the driver pays toward the claim, and it is taken off the payout in many cases.
A claim may be refused if the incident is not covered by the policy, if the policy was not active, if the details given were incorrect in a serious way, or if the incident falls under an exclusion. A claim may also be refused if the driver did not report the incident promptly, or if the driver arranged repairs before the insurer had agreed.
If a claim is refused or reduced, the insurer should explain the reasons in writing. The driver can ask for that explanation to be clarified, and can provide extra evidence if they think the decision is wrong. If the disagreement cannot be resolved, the driver may be able to use a complaints process or an independent dispute service, depending on the market.
How long a claim assessment takes
Simple claims with clear facts and clear photos can be assessed quickly. More complex claims, where fault is disputed or the damage is extensive, take longer. A claim involving injury usually takes longer than a claim for vehicle damage alone, because medical information may be needed.
The driver can help the process move faster by reporting the incident promptly, providing clear photos and notes, answering the insurer questions fully, and keeping copies of all correspondence. A claim reference number should be kept safe, and any change in contact details should be passed to the insurer.
Delays are frustrating, but they do not always mean the claim will be refused. An assessment that takes time is often a sign that the insurer is checking the evidence carefully, rather than a sign of a problem.
This guide explains how claims generally work. It is not personal financial advice. Check your own policy wording before you decide.
How do insurers decide who is at fault?
Insurers weigh the evidence from both sides, including driver statements, photos, witness accounts, police reports and dashcam footage where available. Fault is not always all or nothing, and in some cases both drivers share responsibility. If insurers disagree, they may negotiate between themselves.
What evidence helps a car insurance claim?
Clear photos of the damage and the scene, notes made at the time, witness details, a police reference and dashcam footage all help. The more complete the evidence, the easier it is for the insurer to assess what happened and decide the claim.
Why might a claim be refused?
A claim may be refused if the incident is not covered by the policy, if the policy was not active, if important details were incorrect, or if the incident falls under an exclusion. Late reporting or unauthorised repairs can also cause problems. The insurer should explain the reasons in writing.
How is a written off car valued?
If repair costs are higher than the car value, the insurer may treat the car as a write off and pay its market value at the time of the incident, less the deductible. Market value is based on the car age, condition and mileage, not on the price originally paid.